Very likely, yes, usually as soon as the petition is advertised in The Gazette. If a winding-up order is later made, payments out of the account after the petition was presented can be void, and a liquidator can seek to recover them from whoever received them. Banks do not want to be drawn into that, so in practice they freeze the account. A court validation order can allow the company to keep paying wages and suppliers.
Account frozen or about to be? Call 07361 999123 for a free initial consultation today.
Your free call is with a Solicitor. Have the petition to hand if you can.
Text DIRAID to 82228and we will call you back
Or call us on 07361 999123
First consultation free · No obligation · Nothing to lose
Why banks freeze accounts
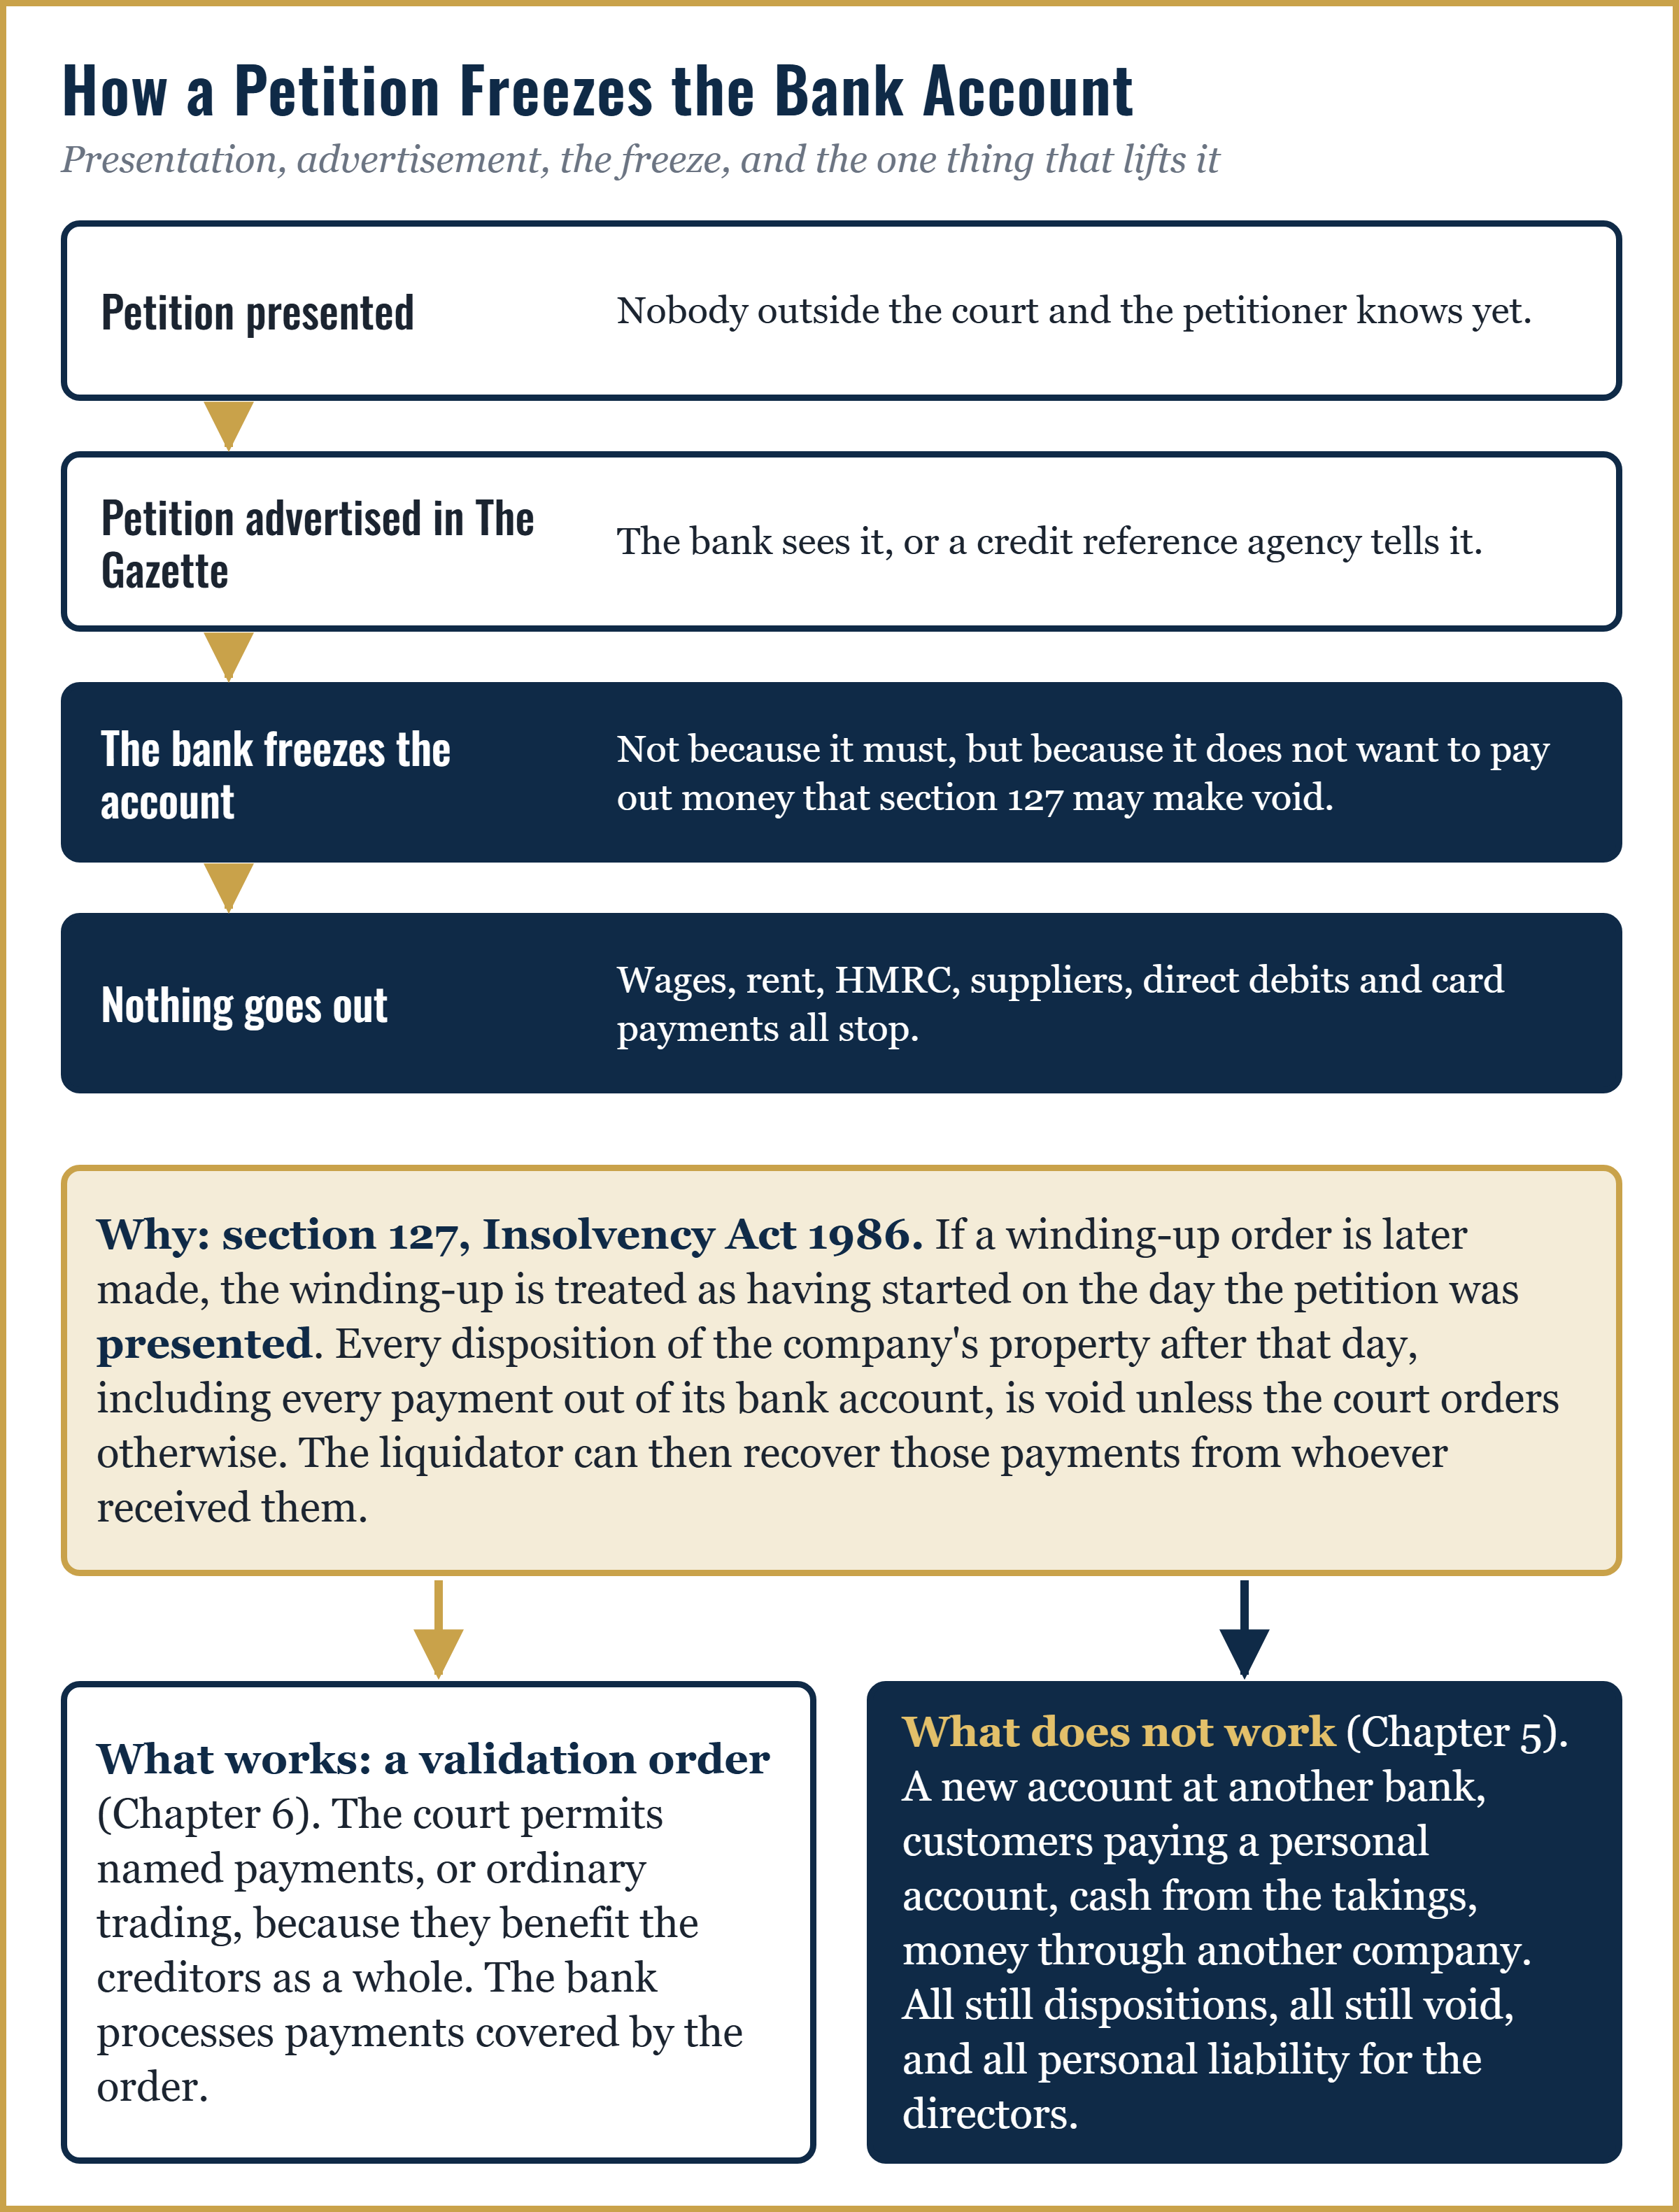
Under section 127 of the Insolvency Act 1986, any disposition of a company's property after a winding-up petition is presented is void if a winding-up order is made, unless the court orders otherwise. Payments out of the company's bank account are dispositions. A bank that keeps processing them risks being drawn into a liquidator's claims, so most banks freeze the account once they learn of the petition, usually from the Gazette advertisement.
How the bank finds out, and when
- The Gazette. Banks and their agents check the advertisements; the freeze usually follows within one to five business days of the notice.
- The credit reference agencies. A petition is flagged on the company's commercial credit file soon after advertisement, and some banks act on the flag.
- The petitioner's solicitors. Some write to the company's bank directly, sometimes before advertisement.
- The company. Telling the relationship manager does not help; the bank's hands are tied by section 127 whoever tells it.
Because petitions are served at the registered office, a director whose post goes elsewhere can learn of the petition from the freeze itself. Check whether there is a petition.
What a freeze looks like
- The account is marked "under review"; online banking becomes view-only; cards are declined.
- Outgoing payments, including wages, rent, HMRC and supplier payments, stop.
- Direct debits, standing orders and card payments fail.
- Customer receipts are accepted but ring-fenced.
- The relationship manager is replaced by the bank's recoveries team, which works to a procedure and cannot be talked round.
- Overdraft and loan facilities may be withdrawn or called in, and any personal guarantee looked at.
It is rarely just one account
Card acquirers and payment providers hold settlements, so takings stop arriving. Invoice finance and factoring facilities stop advancing, often the real cash problem. The failed direct debits put hire purchase, insurance, rent, payroll and pension contributions into arrears, and a lapsed motor policy stops a haulier on day one. Each is a candidate for a validation order, and the list is what to bring to the first conversation with an adviser. The one-page bank checklist sets it out.
What to ask the bank on the day
What is restricted and since when; what triggered it; which payments it will release and against what (nearly always a court order); where receipts are being credited; whether any facility is being called in; and who the contact is now. Get the answers in writing. More in what to ask the bank.
What you can do
- Act before advertisement. Once the notice appears, a freeze usually follows within days.
- Talk to the bank. Ask exactly what it has restricted and on what terms it would release payments.
- Apply for a validation order. The court can authorise specific payments, or continued trading, where this benefits creditors as a whole.
- Use money that is not the company's. A director's or a third party's own funds can pay what the company cannot, because section 127 bites on the company's property; reimbursing them later from the company's account is a disposition in its own right and needs advice.
- Deal with the petition itself. If the debt is disputed, or can be paid or settled properly, ending the petition ends the bank's concern.
After the petition is dismissed
Banks lift the freeze when they see the sealed order dismissing or withdrawing the petition, not when they are told. Send the sealed order to the recoveries team the same day and ask for written confirmation that the restriction is lifted. Then ask the credit reference agencies to record the dismissal, or the flag will go on affecting the company's credit terms for months.
What not to do
- Don't open a new account to move money around the freeze.
- Don't ask customers to pay into a personal or another company's account.
- Don't pay creditors in cash from takings.
Opening another account is not itself unlawful, but it solves nothing: payments out of it are just as void, the new bank runs the same checks and freezes it within days, and a liquidator reads it as evasion. Moving the company's money does not take it outside section 127: payments out of a new account are just as vulnerable, and diverting company receipts to a personal or another company's account can be a void disposition, a breach of duty and a misfeasance claim against the directors personally.
From The Winding-Up Petition Handbook, free for directors.
Key points
- Banks usually freeze accounts once a petition is advertised.
- The reason is section 127: post-petition payments can be void.
- A validation order can unlock payments that benefit creditors.
- Card settlements, invoice finance and direct debits usually stop in the same week.
- Moving money around the freeze can create personal liability.
- The freeze is lifted on sight of the sealed order dismissing the petition.
Frequently asked questions
Can I still pay staff? Not from a frozen account without the bank's agreement, which usually requires a validation order.
Will the freeze lift if the petition is dismissed? Usually, yes. Banks generally lift restrictions once the petition is dismissed or withdrawn.
Can the bank freeze the account before advertisement? It can if it learns of the petition another way, for instance from the petitioner's solicitors.
Does the bank have to freeze the account? No. There is no rule requiring it; the bank does it to avoid processing payments that section 127 may later make void, which is also why it will not be argued out of it.
Keep the business running. Free initial consultation: 07361 999123 or request a call back.